I recently blogged on Siemens Medical Solutions USA v. Commissioner, 167 T.C. No. 5 (July 15, 2026), where the Tax Court invalidated a temporary regulation under IRC §245A as inconsistent with the statute, citing Loper Bright Enterprises v. Raimondo, 603 U.S. 369 (2024). Not quite two weeks before the Tax Court’s opinion, the Court of Federal Claims in Keysight Technologies, Inc. v. United States, __ Fed. Cl. ___ (July 2, 2026), invalidated a different regulation under the Tax Cuts and Jobs Act (“TCJA”), Treas. Reg. §1.951A-2(c)
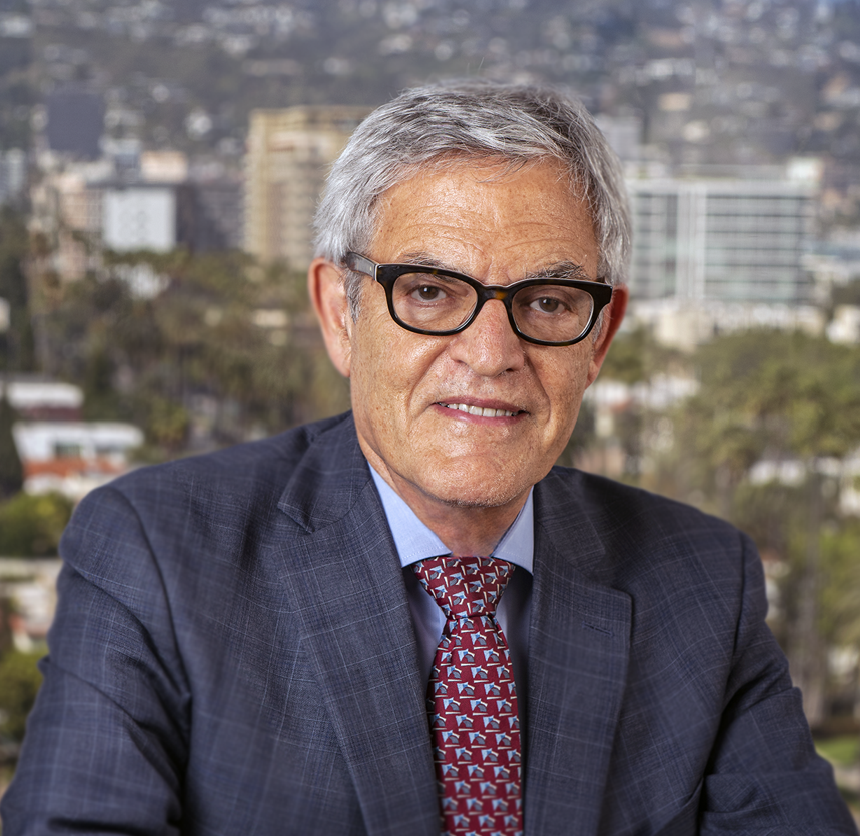
Robert S. Horwitz is a Principal at Hochman Salkin Toscher Perez P.C., former Chair of the Taxation Section, California Lawyers’ Association, a Fellow of the American College of Tax Counsel, a former Assistant United States Attorney and a former Trial Attorney, United States Department of Justice Tax Division. He represents clients throughout the United States and elsewhere involving federal and state administrative civil tax disputes and tax litigation as well as defending clients in criminal tax investigations and prosecutions. In 2022 the Tax Section of the California Lawyers Association awarded him the Joanne M. Garvey Award for lifetime achievement in and contributions to the field of tax law.
For more information, please contact Robert Horwitz at horwitz@taxlitigator.com.


Leave a Reply