Sebastian Voth was recently quoted in a Tax Notes article by Kristen A. Parillo, “Tax Pros: Expanded Access to Tax Court Docs Has Benefits and Risks,” published October 28, 2026. The article discusses the Tax Court’s Administrative Order No. 2026-02, under which motions, supporting briefs and memoranda, and oppositions electronically filed by admitted practitioners on or after January 1, 2027, will be remotely available through DAWSON.
Mr. Voth called the new order “a very positive and practical extension of the court’s 2023 order.” He noted that he and many other tax professionals found the Tax Court’s 2023 expansion of remote access to posttrial and amicus briefs extremely useful in their practices. “Extending this to motions and supporting briefs should make research more efficient, improve transparency, and give us immediate insight into how issues are being framed and argued,” he said.
Sebastian Vothis a Principal at Hochman Salkin Toscher Perez P.C., specializing in tax investigations, litigation and appeals, and complex tax matters. Prior to entering private practice, Mr. Voth served for 15 years at the Internal Revenue Service including most recently as a Special Trial Attorney with the IRS Office of Chief Counsel’s Strategic Litigation Division leading trial teams in all phases of litigation before the Tax Court. During his tenure with the IRS, Mr. Voth served on the leadership team of the nationwide IRS Counsel mentoring program and mentored numerous IRS attorneys. He is the recipient of two Lucite Awards for significant Tax Court opinions and received a 2024 Special Act Award (Strategic Litigation), the 2023 Nationwide Innovator of the Year (LB&I), the 2022 Nationwide Special Trial Attorney of the Year (SB/SE), the 2017 U.S. Department of the Treasury Outstanding Litigator and the 2017 Nationwide Attorney of the Year (SB/SE). Serving as a Special Trial Attorney, Mr. Voth handled some of the IRS’s most significant and complex litigation matters.
We are pleased to announce that Sandra R. Brown, Melissa Briggs and Timothy Bilotta will be speaking on Ethical Issues in Tax Practice: Real-Life Dilemmas, Gray Areas, and Professional Responsibilities at the upcoming Strafford webinar, Wednesday, November 4, 2026 from 10:00 a.m. – 11:50 p.m. (PST).
This webinar will examine the ethical issues tax professionals confront in everyday practice and the professional standards that govern those situations. Our panelists will explore the often difficult line between appropriate tax advocacy and conduct that may violate Circular 230, professional standards, or other ethical obligations.
Sandra R. Brownis a Principal of Hochman Salkin Toscher Perez P.C., where her practice focuses on criminal tax investigations, grand jury matters, litigation, and sentencing matters as well as representing and advising taxpayers involved in complex and sophisticated civil tax controversies, including sensitive-issue audits and administrative appeals and litigation. Ms. Brown’s extensive experience and successes have included many notable cases including two U.S. Supreme Court decisions, numerous 9th Circuit rulings and numerous favorable administrative resolutions for taxpayers involved in IRS investigations and audits. Prior to joining the firm in 2018, Ms. Brown served as the Acting United States Attorney, First Assistant United States Attorney, and Chief of the Tax Division in the Office of the U.S. Attorney, Central District of California; where, with 27 years as a trial lawyer, she personally litigated over 2,000 tax cases.
Melissa Briggsis a Principal of Hochman Salkin Toscher Perez P.C. where she represents clients in civil and criminal tax controversies. Ms. Briggs has over twenty-four years of litigation experience in private, nonprofit, and government practice. Ms. Briggs spent over nine years as an appellate attorney for the U.S. Department of Justice, Tax Division, Appellate Section. She served almost seven years as an Assistant United States Attorney with the United States Attorney’s Office for the Central District of California’s Tax Division. She began her legal career as a law clerk to the Hon. Phyllis A. Kravitch on the United States Court of Appeals for the Eleventh Circuit.
Ms. Briggs is a fellow of the American College of Tax Counsel; American Bar Association, Tax Section, Loretta Collins Argrett Fellowship committee member and mentor; chair of the California Lawyer’s Association Tax Section, Tax Practice and Procedure Committee, and active member of the Women Lawyers Association of Los Angeles.
We are pleased to announce that Evan J. Davis and Philipp Behrendt recently spoke at the Federal Bar Association’s webinar on The Cryptocurrency Reckoning of 2027: Cost Basis Reporting, IRS Enforcement, and Defending Clients When the First 1099-DA Mismatch Arrives that took place on October 28, 2026.
For more than a decade, the IRS pursued cryptocurrency noncompliance through John Doe summonses, blockchain analytics, and the Form 1040 digital-asset question. What it lacked was standardized broker reporting of cost basis. That changes with the 2027 filing season. Brokers reported gross proceeds on Form 1099-DA for sales effected in 2025. For 2026 sales of covered digital assets, they must report basis and acquisition information too.
Sell cryptocurrency transferred in from another exchange or self-custody, and the form may show proceeds with no basis. Miss the wallet-by-wallet rules of Treas. Reg. § 1.1012-1(j), and FIFO fills the gap. Skip the Rev. Proc. 2024-28 safe harbor, and pre-2025 lot allocations are lost. A mismatch draws automated matching, CP2000 notices, and correspondence examinations. Add badges of fraud, and United States v. Ahlgren shows where it can end.
Attendees walked out with methods for reconstructing and substantiating basis from exchange records, wallet records, and blockchain data; a decision framework for qualified amended returns, Form 14457 voluntary disclosure, or defending the filed return; protocols for Kovel arrangements and privilege; and the fraud indicators that mark an eggshell audit.
The program will be available for viewing through the FBA’s portal.
Evan J. Davishas been a principal at Hochman Salkin Toscher Perez P.C. since November 2016. He spent 7.5 years as a DOJ Tax civil litigator and then 11 years as a criminal AUSA in the Office of the U.S. Attorney (C.D. Cal), including 3 years handling civil and criminal tax cases and 8 years as a white-collar prosecutor handling tax and other fraud cases from investigation through jury trial and appeal. As an AUSA, he served as the Bankruptcy Fraud coordinator, Financial Institution Fraud coordinator, and Securities Fraud coordinator. Mr. Davis handles federal and state criminal and civil tax investigations/exams, white-collar defense, cryptocurrency clients, and civil and criminal appellate matters including having litigated the In re Grand Jury attorney-client privilege matter before the U.S. Supreme Court in 2023.
Philipp Behrendtis a Principal at Hochman Salkin Toscher Perez P.C., licensed in California as well as in Germany and assists in advising clients in civil and criminal tax controversies as well as international money laundering investigations stemming from tax avoidance structures. He also focuses on the technical aspects involved in advising voluntary disclosures in connection with DeFis, NFTs, and other crypto assets. Philipp is a Liaison to the Young Lawyer Committee for the ABA Tax Section’s Civil and Criminal Tax Penalties Committee and served on the Beverly Hills Bar Association’s Barristers Board of Governors from 2022 to 2023. Philipp is the Chair of the Beverly Hills Bar Association’s Tax Section, a Liaison.
We are pleased to announce that Dennis Perez, Michel R. Stein and Robert S. Horwitz will be speaking at the upcoming Spidell webinar on Federal and State Residency Matters: Navigating Examination Guidance State Regulations and Remote Workers on Tuesday, November 3, 2026, 10:00 a.m. – 12:00 p.m. (PST).
This webinar will guide tax professionals and advisers on the latest IRS residency examination guidance and California residency issues. California state tax residency rules, and an increase in residency audits and enforcement, require tax professionals to know state residency and income allocation issues, so they can properly advise their clients when these issues arise.
Dennis Perezhas extensive experience in the representation of clients in civil and criminal tax litigation and in tax disputes and controversies before the Internal Revenue Service and all the California taxing agencies. Mr. Perez was formerly a senior trial attorney with District Counsel, Internal Revenue Service, in Los Angeles, California. Mr. Perez is a Certified Tax Specialist, California State Bar Board of Certification and is also a Fellow of the American College of Tax Counsel. He frequently lectures on advanced civil and criminal tax topics at seminars and before national, state and local bar associations and accountancy groups.
He is a co-author of the BNA Portfolio, Tax Crimes, has served as the Chair of the Los Angeles Lawyer Magazine Editorial Board and is the first recipient of the Los Angeles Lawyer Sam Lipsman Service Award for outstanding service to the Los Angeles Lawyer Magazine. Mr. Perez was the 2025 recipient of the Joanne M. Garvey Award, given annually to recognize lifetime achievement and outstanding contributions to the field of tax law by a senior member of the California tax bar. He is past Chair of the Tax Procedure and Litigation Committees of the Taxation Sections of the State Bar of California and the Los Angeles County Bar Association. Mr. Perez is past President of the Alumni Board for the UCLA School of Law and has served as an Adjunct Professor, Golden Gate University, Graduate School of Taxation.
Michel R. Stein,a principal of Hochman Salkin Toscher Perez P.C., is a nationally recognized tax attorney with nearly 30 years of experience in tax controversy and planning for individuals and business entities. He is widely respected for his ability to resolve complex and sensitive tax controversies before the Internal Revenue Service and the California Franchise Tax Board, including matters involving significant civil and criminal exposure, and is a trusted resource to clients and advisors navigating the most challenging areas of federal and state tax law. His commentary and insights have been featured in leading tax publications, webinars, and media outlets addressing emerging issues in tax enforcement and policy.
Mr. Stein has represented hundreds of clients in civil tax examinations, administrative appeals, and litigation before the U.S. Tax Court, U.S. District Courts, California Superior Court, and the U.S. Courts of Appeals. He routinely advises and defends clients in matters involving California Residency, Digital Assets and Cryptocurrency Investigations, High-Net-Worth Taxpayer Compliance and Examination, Domestic and International Tax Compliance, Voluntary Disclosures and Streamlined Filings, Challenges to Listed and Reportable Transactions, Partnership Tax and Audit Rules, Employment Tax and Worker Classification Issues, as well as tax controversies arising from Complex Real Estate and Business Transactions. He began his legal career as an Attorney Advisor to Special Trial Judge Larry Nameroff of the U.S. Tax Court and is a Certified Specialist in Taxation Law by the State Bar of California.
Robert S. Horwitzis a Principal at Hochman Salkin Toscher Perez P.C., former Chair of the Taxation Section, California Lawyers’ Association, a Fellow of the American College of Tax Counsel, a former Assistant United States Attorney and a former Trial Attorney, United States Department of Justice Tax Division. He represents clients throughout the United States and elsewhere involving federal and state administrative civil tax disputes and tax litigation as well as defending clients in criminal tax investigations and prosecutions. In 2022 the Tax Section of the California Lawyers Association awarded him the Joanne M. Garvey Award for lifetime achievement in and contributions to the field of tax law.
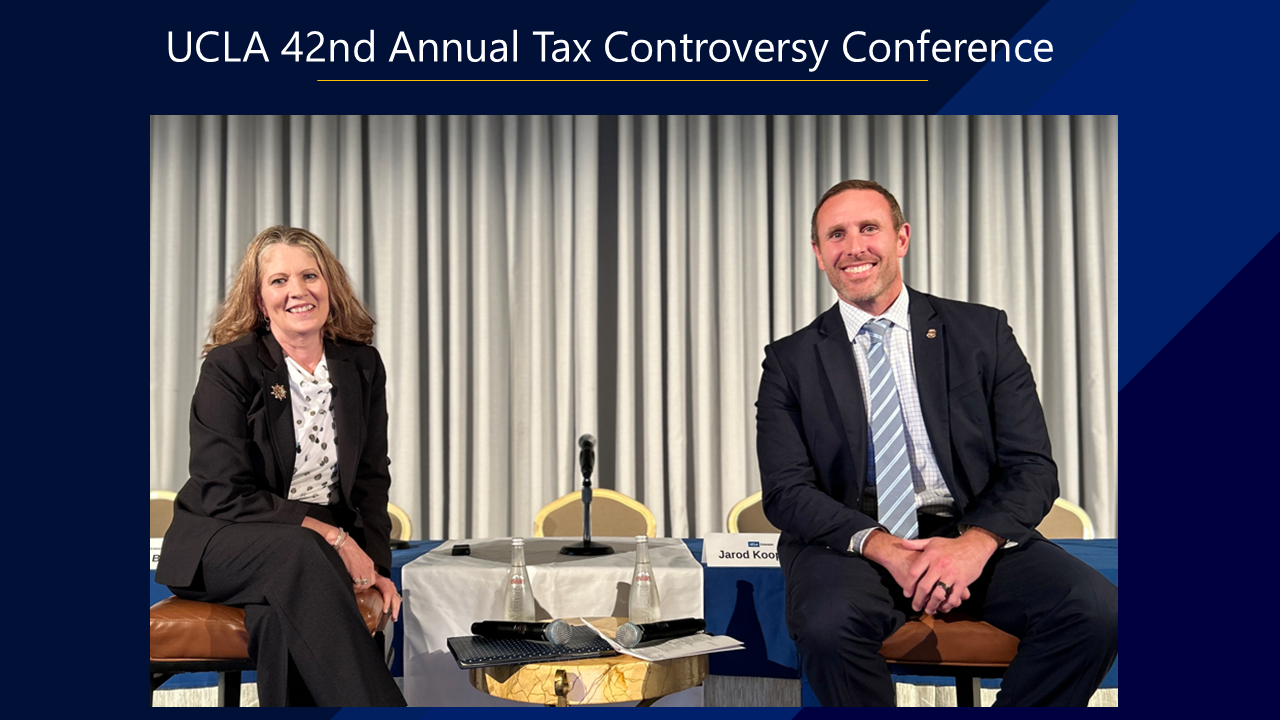
Sandra R. Brown was recently quoted in a recent Forbes article by Guinevere Moore, “Confession May Soon Cost Less: IRS Promises Lower Penalties For Voluntary Disclosure,” published October 23, 2026.
The article covers remarks by IRS Chief Tax Compliance Officer and Criminal Investigation Chief Jarod Koopman at the UCLA Extension Tax Controversy Conference, where Sandra Brown interviewed Mr. Koopman who stated that the IRS is “very close” to releasing a revised Voluntary Disclosure Program.
Commenting on the announcement, Ms. Brown explained:
“In an environment where the IRS has faced massive workforce reductions and reorganizations, a shift in this program to a fresh start focus that prioritizes long-term reintegration of non-compliant filers is a clear win-win for tax administration.”
Sandra R. Brownis a Principal of Hochman Salkin Toscher Perez P.C., where her practice focuses on criminal tax investigations, grand jury matters, litigation, and sentencing matters as well as representing and advising taxpayers involved in complex and sophisticated civil tax controversies, including sensitive-issue audits and administrative appeals and litigation. Ms. Brown’s extensive experience and successes have included many notable cases including two U.S. Supreme Court decisions, numerous 9th Circuit rulings and numerous favorable administrative resolutions for taxpayers involved in IRS investigations and audits. Prior to joining the firm in 2018, Ms. Brown served as the Acting United States Attorney, First Assistant United States Attorney, and Chief of the Tax Division in the Office of the U.S. Attorney, Central District of California; where, with 27 years as a trial lawyer, she personally litigated over 2,000 tax cases.
In late September 2026, the U.S. Government Accountability Office published GAO-26-107810, Tax Fraud: The Federal Government Loses an Estimated $116 Billion to $304 Billion Annually. Their report analyzed the scope of federal tax fraud and proposed IRS actions that may help prevent, detect, and respond to tax fraud.
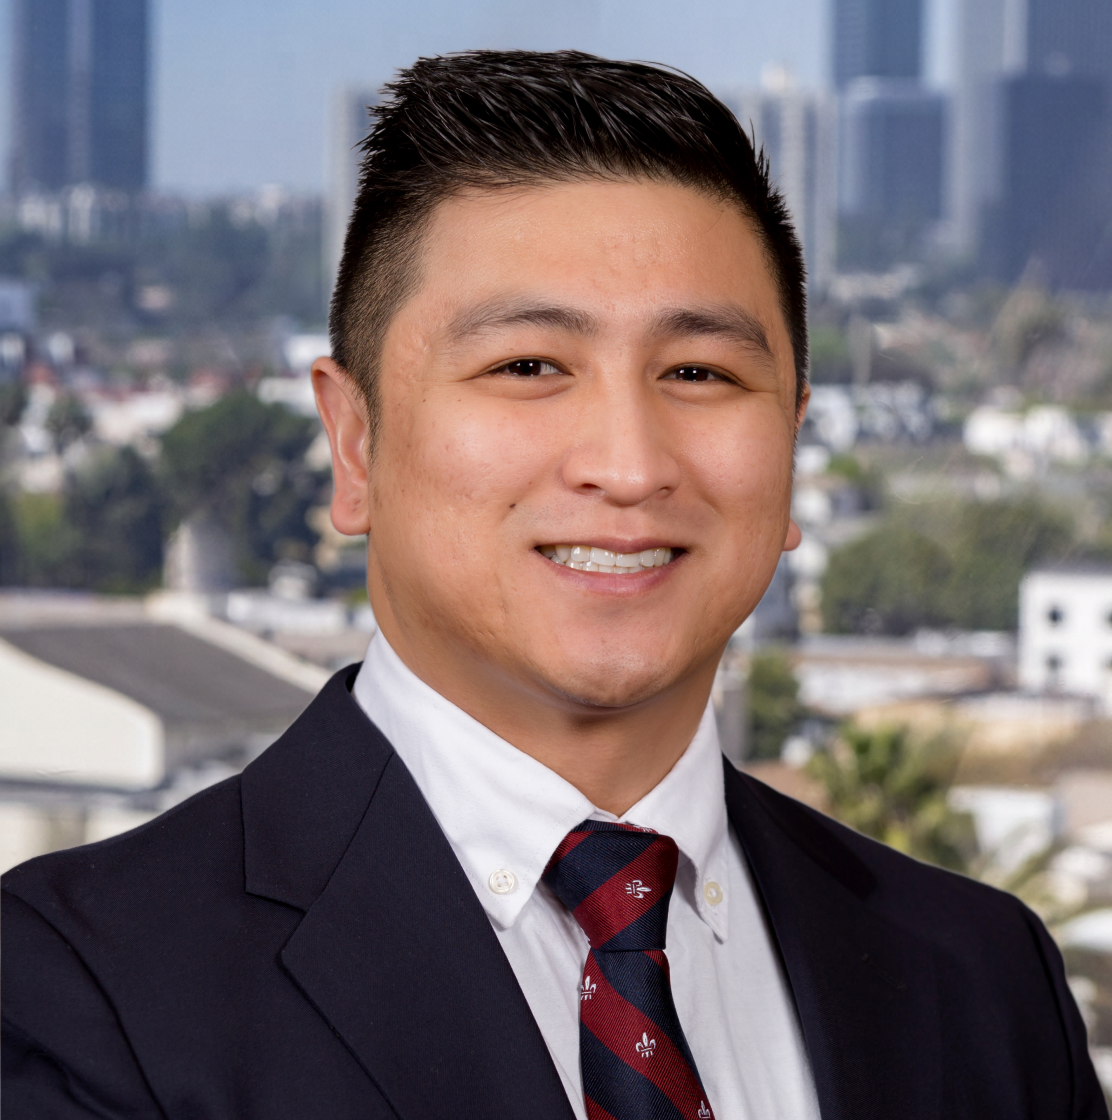
Marc Montanois an Associate at Hochman Salkin Toscher Perez P.C. where his focus is on representation of clients in civil and criminal tax litigation and investigations. Mr. Montano joined the firm in 2026 while attending NYU Law School, where he received his LL.M. in Taxation.
Prior to joining the firm, Mr. Montano interned with the IRS Office of Chief Counsel where he worked on matters including a case stemming from one of the largest tax fraud cases in history of over $7 billion in fraudulent tax deductions. His experience at the IRS included successfully arguing a Motion to Dismiss before the U.S. Tax Court, working on tax shelter cases before trial and matters before the IRS Independent Office of Appeals. Mr. Montano also interned with the United States District Court for the Southern District of Indiana, where he gained experience in federal civil and criminal litigation.
On October 8, 2026, Assistant Attorney General Colin M. McDonald, who leads the U.S. Department of Justice’s National Fraud Enforcement Division (NFED), announced the division’s comprehensive anti-fraud strategy pursuant to the newly issued Directive 26-12: Corporate Enforcement in the Fight Against Fraud.
Sandra R. Brownis a Principal of Hochman Salkin Toscher Perez P.C., where her practice focuses on criminal tax investigations, grand jury matters, litigation, and sentencing matters as well as representing and advising taxpayers involved in complex and sophisticated civil tax controversies, including sensitive-issue audits and administrative appeals and litigation. Ms. Brown’s extensive experience and successes have included many notable cases including two U.S. Supreme Court decisions, numerous 9th Circuit rulings and numerous favorable administrative resolutions for taxpayers involved in IRS investigations and audits. Prior to joining the firm in 2018, Ms. Brown served as the Acting United States Attorney, First Assistant United States Attorney, and Chief of the Tax Division in the Office of the U.S. Attorney, Central District of California; where, with 27 years as a trial lawyer, she personally litigated over 2,000 tax cases.
I recently blogged on Siemens Medical Solutions USA v. Commissioner, 167 T.C. No. 5 (July 15, 2026), where the Tax Court invalidated a temporary regulation under IRC §245A as inconsistent with the statute, citing Loper Bright Enterprises v. Raimondo, 603 U.S. 369 (2024). Not quite two weeks before the Tax Court’s opinion, the Court of Federal Claims in Keysight Technologies, Inc. v. United States, __ Fed. Cl. ___ (July 2, 2026), invalidated a different regulation under the Tax Cuts and Jobs Act (“TCJA”), Treas. Reg. §1.951A-2(c)
Robert S. Horwitzis a Principal at Hochman Salkin Toscher Perez P.C., former Chair of the Taxation Section, California Lawyers’ Association, a Fellow of the American College of Tax Counsel, a former Assistant United States Attorney and a former Trial Attorney, United States Department of Justice Tax Division. He represents clients throughout the United States and elsewhere involving federal and state administrative civil tax disputes and tax litigation as well as defending clients in criminal tax investigations and prosecutions. In 2022 the Tax Section of the California Lawyers Association awarded him the Joanne M. Garvey Award for lifetime achievement in and contributions to the field of tax law.
The Court of Appeals for the District of Columbia Circuit affirmed the district court’s order enjoining the IRS from sharing taxpayer return information with Immigration and Customs Enforcement (“ICE”) in Center for Taxpayer Rights v. I.R.S., 2026 U.S. App. LEXIS 27506 (Sept. 8, 2026).
As you probably recall, shortly after his inauguration in January 2025, Pres. Trump began a crackdown on immigrants who were here illegally, having either overstayed their visas or having entered the United States illegally. This crackdown took the highly publicized and controversial form of armed bands of ICE agents combing the streets of American cities, arresting people who they believed were here illegally, attacking protestors and otherwise acting in a way which could be described as antithetical to the concept of ordered liberty.
Robert S. Horwitzis a Principal at Hochman Salkin Toscher Perez P.C., former Chair of the Taxation Section, California Lawyers’ Association, a Fellow of the American College of Tax Counsel, a former Assistant United States Attorney and a former Trial Attorney, United States Department of Justice Tax Division. He represents clients throughout the United States and elsewhere involving federal and state administrative civil tax disputes and tax litigation as well as defending clients in criminal tax investigations and prosecutions. In 2022 the Tax Section of the California Lawyers Association awarded him the Joanne M. Garvey Award for lifetime achievement in and contributions to the field of tax law.
We previously blogged about the Tax Court’s decision in Big Apple Tompkins Realty LLC v. Commissioner, which held that the deadline for filing a petition challenging a Notice of Final Partnership Adjustments (“FPA”) under Internal Revenue Code (“IRC”) § 6234(a) was not jurisdictional. That case left an unanswered question: can the filing deadline be equitably tolled. In Kings Road Property LLC v. Commissioner, 165 T.C. No. 11 (September 21, 2026), the Tax Court answered the question in the affirmative. Based on the facts in the case, the Court held that the filing deadline was equitably tolled.
Robert S. Horwitzis a Principal at Hochman Salkin Toscher Perez P.C., former Chair of the Taxation Section, California Lawyers’ Association, a Fellow of the American College of Tax Counsel, a former Assistant United States Attorney and a former Trial Attorney, United States Department of Justice Tax Division. He represents clients throughout the United States and elsewhere involving federal and state administrative civil tax disputes and tax litigation as well as defending clients in criminal tax investigations and prosecutions. In 2022 the Tax Section of the California Lawyers Association awarded him the Joanne M. Garvey Award for lifetime achievement in and contributions to the field of tax law.
Legal Disclaimer. This Report only provides general information about the law and does not, under any circumstances, constitute legal advice in any manner. The facts of each situation are unique and you should not act or refrain from acting in any manner based on any information contained or referenced in this Report at any time without first obtaining the advice of competent professional legal counsel. This site contains links to third-party internet sites. We are not responsible in any manner for, and make no representations or endorsements of any kind whatsoever with respect to, any third-party internet sites or with respect to any information, products or services that such internet sites might offer or provide.